Financing Your Rocky Point Purchase: What Foreign Buyers Actually Need to Know
Most of the transactions I see in Rocky Point are paid in full at closing. That does not necessarily mean the buyer had the entire purchase price sitting in a checking account.
Some buyers obtain funds in the United States or Canada—through savings, the sale of another property, or a loan secured by a home they already own—and then complete the Mexican purchase without financing from the seller or the developer.
The financing paths I most often see buyers use successfully are:
- Funds arranged in their home country (U.S. or Canada)
- Seller financing
- Developer financing
The financing I most commonly encounter within Rocky Point transactions is seller financing or developer financing. Availability and terms vary considerably from one property and one seller to the next. There is no single mortgage program that applies to every foreign buyer or every Rocky Point property.
What about Mexican bank mortgages?
Mexican banks do offer mortgage products, but their borrower qualifications, property requirements, documentation, interest rates, fees, and permitted uses are lender-specific.
Many of my American and Canadian clients do not pursue a conventional Mexican bank mortgage because they may not meet the lender’s residency, income, tax, credit, or property-use requirements—or because the available terms are not competitive for their circumstances. As a practical matter, the financing options I most often see my clients use successfully are funds arranged in their home country, seller financing, and developer financing.
Financing Options Foreign Buyers Commonly Use in Rocky Point
| Option | Typical role in a Rocky Point purchase | What to confirm early |
|---|---|---|
| Home-country funds (cash / HELOC / other loan) | Seller paid in full at closing | Qualification, amount, funding timeline, rate structure |
| Seller financing | Seller carries part of the price | Down payment, rate, amortization, balloon / maturity, default terms |
| Developer financing | Project-specific payment plan | Term, rate, trust/title timing, prepayment, default terms |
| Mexican bank mortgage | Available, but often not the path my U.S. and Canadian buyers use | Lender-specific residency, income, credit, property-use rules |
Why Financing Should Shape Your Rocky Point Search Early
Financing needs to be addressed at the beginning, not after we have negotiated the property. Someone considering a home equity line of credit (HELOC) or another home-country loan should find out whether they qualify, how much they can borrow, how long funding will take, whether the rate can change, and what the monthly and long-term obligations will be before they become serious about a specific property.
Seller financing is different because its availability and terms depend on the individual property and seller. Even so, buyers should understand that seller financing commonly requires a substantial down payment and may require a balloon payoff within several years. That knowledge should shape the search from the beginning.
Not every property offers seller or developer financing. If financing is essential and the seller will not provide it, that property may need to be removed from consideration unless the buyer can arrange another source of funds.
Financing becomes part of the property-search criteria, just like location, price, property type, and intended use. Address it at the beginning, not after negotiating a property.
Why I ask financial questions early
The purpose of asking financial questions early is not to pressure or judge the buyer. It is to protect the buyer’s time and keep the search focused on properties that can realistically be purchased under their actual funding plan.
It does not make sense to negotiate a property and only later discover that the buyer has not applied for the HELOC or other funding on which the purchase depends.
Seller Financing in Rocky Point: Monthly Payment vs Balloon
The MLS listing may indicate that a seller is willing to consider financing. That does not mean the seller will accept every proposed structure. Each seller decides what down payment, interest rate, payment amount, amortization schedule, and payoff date they will accept.
- Most properties that offer seller financing ask for between 30% and 50% down.
- Most have a balloon payment due between 3 and 5 years.
In recent transactions, I have often seen sellers request a substantial down payment—commonly between 30% and 50%. The monthly payment may be calculated using a longer amortization schedule, while the remaining balance becomes due much sooner through a balloon payment. For example, the payment might be calculated as though the loan will be paid over 15 or 20 years, even though the remaining balance must be paid after three to five years.
Amortization period vs. balloon date
| Amortization period | Balloon-payment date |
|---|---|
| Used to calculate the monthly payment | When the remaining balance must be paid |
| Example: 15 or 20 years | Example: 3 to 5 years |
The amortization period and the balloon-payment date are not the same thing. Buyers need to understand both.
Interest rates and all other terms are negotiable only to the extent the particular seller is willing to negotiate them. The terms I have recently encountered vary, so any published numerical range should be treated as an example from a specific period—not a permanent market rule.
Before making an offer
- Purchase price and required down payment
- Interest rate and whether it can change
- Monthly payment
- Amortization period
- Maturity date and balloon payment
- Currency and payment method
- Late fees, grace periods, and cure rights
- Prepayment rights or penalties
- Required insurance, taxes, and HOA payments
- Ownership or trust timing
- Default provisions and remedies
- Professional and closing expenses
The advertised monthly payment is not enough information by itself. Buyers need to understand the complete obligation and what happens at every stage of the purchase and financing arrangement.
They should also understand what happens to their down payment, prior payments, possession, improvements, and ownership rights if they cannot complete the agreement. Those consequences depend on the specific documents, governing law, and facts of the transaction—not on a general rule.
Browse current Sandy Beach homes and condos where the seller or developer offers financing.
View Properties Offering Financing
Developer Financing and Home-Country Loans
Developer financing
Developer financing is property- and project-specific. In transactions I have encountered, the buyer may provide a substantial down payment and make payments over an agreed period.
Some developers offer longer repayment schedules than an individual seller might offer, but the rate, term, payment schedule, maturity date, collateral, default provisions, title or trust timing (see our guide to the Mexican bank trust (fideicomiso)), and prepayment rules must all be reviewed for the particular development. An advertised monthly payment should never replace a review of the complete agreement and total obligation.
HELOCs and other home-country loans
Some buyers consider a HELOC or another loan secured by property they own in the United States or Canada. That can provide funds for the Rocky Point purchase and allow the seller to be paid in full at closing.
However, a HELOC is secured by the buyer’s existing home. Many HELOCs have variable interest rates, which means monthly payments can change. Failure to meet the obligation can place the securing home at risk.
Buyers should compare the complete borrowing cost and consult their lender and financial or tax advisers before using home equity for an international property purchase. I do not present a HELOC as inherently better or worse than other options; it is simply one approach some buyers explore carefully with their own advisers.
Cross-Border Mortgages and Cash Offers in Rocky Point
Cross-border mortgage programs
It means buyers should not rely on a lender’s advertising until they have confirmed eligibility, property coverage, underwriting requirements, interest rate, fees, funding timetable, lien and trust requirements, and actual history of completed transactions in Rocky Point. If a dependable product becomes available, this information should be updated.
Offers without seller financing
An offer that does not require seller financing may be more attractive to some sellers and developers. It may create more negotiating flexibility because the seller receives the balance at closing and does not remain involved as a lender.
That does not guarantee a discount. The amount of additional leverage depends on the property, price, competition, seller’s priorities, and proposed terms.
Preparing Your Total Rocky Point Purchase Budget
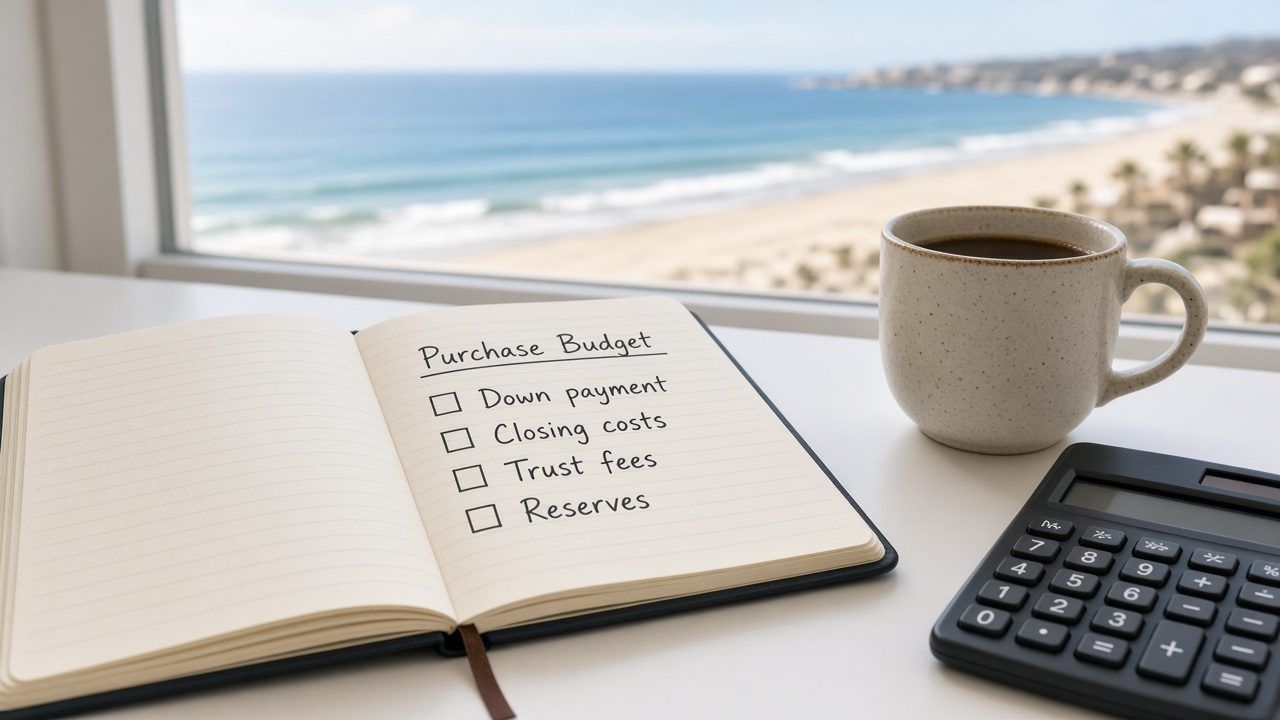
The down payment is only one part of the amount required. Buyers should also plan for the earnest-money deposit, professional and closing expenses, trust-related expenses when applicable, inspection, insurance, furnishings or improvements, HOA charges, utilities, and reserves for ownership and maintenance.
Some costs may occur at different stages depending on the financing and ownership structure.
Buyers should request transaction-specific estimates and ask when each amount will become due.
If you are not financially ready yet
If someone is not yet financially ready, they can still learn about the market, communities, purchasing process, and realistic ownership expenses. Serious property-specific shopping should wait until the buyer understands the likely source, amount, cost, and timing of the funds needed to complete a purchase.
Common Questions About Financing a Rocky Point Purchase
Can foreign buyers get a mortgage in Rocky Point?
Mexican banks do offer mortgages, but qualifications and terms are lender-specific. Many of my American and Canadian clients do not pursue a conventional Mexican bank mortgage. The paths I most often see work are home-country funds, seller financing, and developer financing.
How much down payment is typical for seller financing?
In recent transactions, sellers offering financing commonly ask for about 30% to 50% down. Terms vary by seller and property; treat this as experience, not a rule.
What is a balloon payment in Rocky Point seller financing?
The monthly payment may be calculated on a long amortization (for example 15–20 years) while the remaining balance comes due much sooner — often in about 3 to 5 years. The amortization period and the balloon date are not the same thing.
Should I arrange financing before shopping for a property?
Yes. Financing should shape the search from the beginning. Not every property offers seller or developer financing, and home-country loans need qualification and timing confirmed before you get serious about a specific home.
What costs belong in my total purchase budget besides the down payment?
Plan for earnest money, professional and closing expenses, trust-related costs when applicable, inspection, insurance, furnishings or improvements, HOA charges, utilities, and ownership reserves. Costs that are postponed are not necessarily eliminated.
Related guides: Buyer Overview · Closing Costs and Fees · Mexican Bank Trust · From Offer Through Closing · Buying with a U.S. LLC · Sandy Beach homes with financing
Let’s Talk About Your Financing Options
If you are considering a Rocky Point property and want to understand which financing paths may fit your situation, I am happy to discuss the options that have actually closed for buyers in similar circumstances.
Contact Joseph+1 520.339.1392 · 638.105.3597